
The actor, content creator and entrepreneur has shared insights into her reported property purchases in France and Morocco, offering a personal perspective on financial planning, borrowing and long-term wealth creation.
Financial independence is often discussed in terms of salaries, career growth and savings. For Soundous Moufakir, the conversation also involves property ownership, financial planning and the decisions that helped her build assets while pursuing a career across different industries.
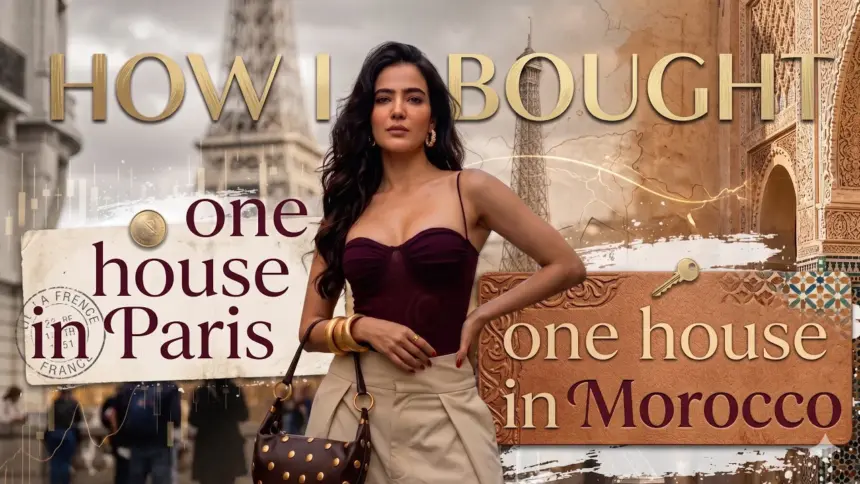
Moufakir, known for her appearances on Indian reality television and her work as a content creator and entrepreneur, has spoken about purchasing properties in Paris, France, and Morocco before turning 30. In a video shared on her YouTube channel, she discussed her experience with real estate and the financial decisions involved in pursuing long-term security.
Her account offers a personal perspective on a subject that can feel inaccessible to younger professionals: how to approach major financial commitments while navigating an uncertain career.
The details of her property purchases and financing should be understood in the context of her own account. Property ownership, borrowing costs and investment returns vary significantly between individuals, markets and circumstances.
Beyond a salary: Rethinking financial independence
Financial independence is not determined by income alone. Savings habits, debt obligations, investment decisions and spending patterns can all influence a person’s ability to build long-term financial security.
Moufakir’s reported property purchases illustrate one approach to building assets while managing a career that does not necessarily follow a conventional employment path.
For actors, creators and entrepreneurs, income can fluctuate considerably. Projects may generate substantial earnings during certain periods, while other months bring fewer opportunities. Planning around those fluctuations can be as important as increasing income.
A financial strategy that accounts for living expenses, emergency savings, debt repayments and future goals can help individuals make decisions without relying entirely on their next payment or contract.
Property ownership may form part of that strategy, but it is not the only route to financial independence. Its suitability depends on affordability, liquidity needs, investment objectives and the risks associated with a particular property.
Buying property in Paris and Morocco
Moufakir has described purchasing properties in two countries before reaching her thirties: Paris in France and Morocco, where she has personal ties.
International property ownership introduces considerations that go beyond the purchase price. Buyers must understand local property laws, financing requirements, taxes, insurance, maintenance expenses and the costs associated with managing a property from another country.
Currency movements can also affect the value of an investment when income, loan repayments and property expenses are denominated in different currencies.
For buyers considering a similar route, the headline value of a property is only one part of the financial picture. The outstanding mortgage, purchase costs, recurring expenses and the time required to sell an asset can materially influence the owner’s financial position.
Moufakir’s experience brings attention to the importance of understanding these commitments before pursuing property as a long-term investment.
The role of loans in building wealth
Borrowing is often a central part of property purchases. A mortgage can allow a buyer to acquire an asset without paying the entire purchase price upfront, but it also creates a financial obligation that must be managed over time.
The affordability of a loan depends on factors such as the interest rate, repayment schedule, loan duration, income stability and the borrower’s ability to meet unexpected expenses.
A low interest rate can reduce borrowing costs, but the full terms of the loan matter. Buyers should consider whether the rate is fixed or variable, the remaining loan balance, additional fees and the consequences of changes in income or interest rates.
Moufakir has discussed the financing decisions behind her property ownership. Her account highlights why understanding loan structures and repayment commitments is important when building assets.
However, her circumstances should not be treated as a universal formula. Financing terms available to one buyer may not be available to another, and a strategy that works for one person’s income and risk tolerance may be unsuitable for someone else.
Financial discipline during an unpredictable career
Building a career in entertainment can involve periods of uncertainty. Brand partnerships, acting assignments and content opportunities may vary in frequency and value, making financial planning especially relevant.
Moufakir’s professional journey spans entertainment and entrepreneurship. Managing financial commitments alongside these pursuits requires an understanding of how present income can support future obligations.
For professionals with irregular earnings, practical steps may include maintaining an emergency fund, separating business and personal expenses, budgeting for taxes and reviewing loan repayments against conservative income estimates.
These measures do not eliminate financial risk, but they can make major decisions easier to evaluate and help prevent short-term spending from undermining long-term goals.
The broader lesson is that financial planning is an ongoing process. It requires regular reviews as income, responsibilities and personal priorities change.
Why property ownership matters to the conversation about women’s financial independence
Property ownership can represent financial security, personal autonomy and a long-term investment objective. For women building careers in entertainment, business or other competitive fields, discussions about money can also encourage greater transparency around financial decision-making.
Moufakir’s account offers an opportunity to discuss how women can approach major financial goals without assuming that a particular career path or income level is the only route to success.
Yet financial independence should not be reduced to owning property by a certain age. A person’s financial position also depends on debt, liquid savings, income stability, insurance, retirement planning and other assets and liabilities.
The more useful question is not whether everyone should purchase property before turning 30, but how individuals can make informed choices that reflect their own circumstances and long-term objectives.
Access to reliable financial information, realistic budgeting and an understanding of risk can help people make those choices with greater confidence.
What aspiring investors can learn from Soundous Moufakir’s story
Moufakir’s reported experience with property in France and Morocco provides several useful starting points for people considering their own financial goals.
First, understand the full cost of an investment rather than focusing only on its headline price. Purchase expenses, financing costs, maintenance and taxes all affect the eventual outcome.
Second, assess debt against realistic income expectations. A repayment plan should remain manageable even when earnings fluctuate or unexpected expenses arise.
Third, maintain sufficient liquidity. Property can be valuable, but it is not always easy to sell quickly without accepting a lower price or incurring additional costs.
Finally, distinguish between a personal success story and a financial recommendation. An individual’s experience can provide useful questions to consider, but it cannot establish that the same strategy will work for everyone.
Hunterfly Take
Soundous Moufakir’s reported property purchases in Paris and Morocco offer a personal entry point into a broader discussion about financial independence, real estate and career uncertainty.
Her story highlights the importance of thinking beyond monthly earnings and considering how savings, borrowing and asset ownership fit into a longer-term financial plan.